Search This Blog

Thursday, December 5, 2024

Fannie Mae CEO reveals what's really behind rising mortgage rates

 Homeowners shouldn't count on lower rates; they should build strong credit so they can qualify for the most affordable loan

A common misconception is that Fed rate cuts automatically mean lower mortgage rates.

The U.S. Federal Reserve cut a key interest rate for the second time in two months. So, interest rates on mortgages should come down along with it, right? Guess again.

After the first cut in September, mortgage rates moved up nearly 50 basis points (or half a percentage point). Moreover, few expect mortgage rates to fall after the most recent cut, once again disappointing those looking to buy a home and prompting questions about what really drives mortgage rates.

A common misconception is that Fed rate cuts automatically mean lower mortgage rates. However, the Fed does not set mortgage rates. Instead, mortgage rates are influenced far more by longer-term Treasury bond yields, which, in turn, are driven by investor expectations of broader economic and financial conditions.

Two primary factors drive mortgage rates:

1. The "base rate": This rate is tied to yields on medium-term U.S. Treasury bonds, ordinarily 10-year bonds. The 10-year Treasury BX:TMUBMUSD10Y is the risk-free alternative for investors when deciding how much return they want when they buy a typical mortgage - usually in the form of a mortgage-backed security, or MBS.

Unlike the short-term fed funds rate, the 10-year Treasury yield is set by the market, not the Federal Reserve. Private investors determine Treasury yields based on all kinds of factors, including expectations for economic growth, inflation, and future policy changes. Ten-year Treasury yields can and do move independently of short-term rates, as they have in the last month.

2. The mortgage "spread": This is the premium that investors require to cover the extra risks associated with buying MBS, as well as lenders' costs to underwrite, originate, and securitize mortgages. Investors, for example, focus on prepayment risk, or the risk that homeowners exercise their right to pay off their 30-year fixed-rate mortgage earlier than the mortgage term, typically via either a refinance or sale of the home. When bond market volatility rises (as it has), prepayment risk rises. Spreads can also widen or narrow based on changes in lenders' costs.

The spread plus the base rate equals the mortgage rate. Changes to either of these can influence whether mortgage rates rise or fall.

The Fed's September and November rate cuts had been signaled long in advance, causing investors to plan and act accordingly. So the actual event was already largely priced into 10-year Treasury yields. Then, shortly after the first Fed action in September, strong economic data and labor-market data pointed to a better-than-expected outlook. When paired with market expectations that Treasury issuance may increase in the years ahead, Treasury bond prices dropped, pushing the yield higher. The resulting 0.70% boost in 10-year Treasury yields pushed up mortgage rates rather significantly in a short period of time.

Mortgage rate increases might be better viewed as simply a return to historical norms.

Mortgage rates currently are at roughly 7%. The increase in the 10-year Treasury bond yield was the main reason mortgage rates moved higher. Notably, the spread - the other component of mortgage interest rates - held relatively stable during the same period.

It's important for mortgage investors, the housing market, and consumers to understand that it is unlikely we will again see the low mortgage rates we had during the COVID-19 pandemic, when a unique combination of monetary and fiscal policy sent rates to near all-time lows.

In fact, current mortgage rates and Fannie Mae's forecast for 2025 rates are well in line with rates over the past several decades. Since 1990, the 30-year fixed-rate mortgage has averaged 6%. Consequently, recent rate increases might be better viewed as simply a return to historical norms after a relatively brief period of abnormal lows, spurred by a once-in-several-generations pandemic.

The implications are wide-ranging. Mortgage investors favor certainty - but today's market carries a lot of uncertainty. In addition to the normal uncertainty around Fed rate moves, there is the effect - or lack of effect - of the Fed reducing its large mortgage-backed securities (MBS) portfolio (initially created during the Great Financial Crisis). Also, future regulation changes could provide incentives or disincentives for banks and other investors to hold MBS on their books, moves that could affect MBS prices and attractiveness as investments.

Higher mortgage rates for longer may continue to weigh down demand and home sales.

For home buyers, higher rates for longer may continue to weigh down demand and home sales. The Mortgage Bankers Association recently reported that mortgage demand has fallen 41% since rates started rising again in September. As supply continues to be constrained and if rates continue to be in line with historical norms (but higher than during COVID), Fannie Mae economists do not predict any large uptick in home sales in 2025.

For potential homebuyers, the takeaway is that they shouldn't count on Fed rate cuts to lower mortgage rates. Instead, they should focus on building the strongest possible credit record to qualify for the lowest rate lenders offer. And, as always, first-time buyers should get as smart as possible about the home-buying process so that when the opportunity arises, they can get into a home and mortgage that sets them up for long-term success.

https://www.morningstar.com/news/marketwatch/20241205336/fannie-mae-ceo-reveals-whats-really-behind-rising-mortgage-rates

Sunday, December 1, 2024

"This Is Nuts": NYC Pays Pakistani-Owned Roosevelt Hotel $220 M To House Illegal Aliens

 Americans should be outraged by New York City's $220 million sweetheart deal with Pakistan to lease the prestigious Roosevelt Hotel in Midtown Manhattan as a luxury shelter for illegal aliens. The most alarming issue is that NYC paid a foreign government to help house the migrants.

X user John LeFevre resurfaced a 2023 news story, first published by The Economic Times, regarding Pakistan's decision to lease the iconic Roosevelt Hotel to the local government, sympathetic to globalist policies, such as open borders. 

For some context, Pakistan has owned the Roosevelt Hotel since 1979. State-owned Pakistan International Airlines acquired the trophy property through its investment arm, PIA Investments Limited. 

According to the 2023 report, the lease agreement spans three years, during which NYC stuffed thousands of illegal aliens into the 1,250-room hotel like cattle—funded entirely by taxpayers. This arrangement has sparked outrage about how NYC paid a foreign gov't to help support the invasion of the third world into a first-world city.

"The hotel is owned by the government of Pakistan, and the deal was part of a $1.1 billion IMF bailout package to help Pakistan avoid defaulting on their international debt," LeFevre wrote on X. 

According to the public records website The Org, Najeeb Samie is a director at Roosevelt Hotel Corporation, as well as a director at Habib Bank and board member and managing director at PIA Investments.

Samie's connection with Habib Bank is alarming, given that in 2017, the New York State Department of Financial Services fined the Pakistani bank $225 million and surrendered its license to operate in the US over compliance failures in its New York branch, such as weaknesses in monitoring transactions for potential links to terrorism financing and sanctions evasion. 

Meanwhile, the Department of Government Efficiency, aka DOGE's Vivek Ramaswamy (also led by Elon Musk), is livid over NYC funding a foreign gov't entity with taxpayer dollars in supporting the migrant invasion. He called the migrant housing scheme totally "nuts":

"A taxpayer-funded hotel for illegal migrants is owned by the Pakistani government which means NYC taxpayers are effectively paying a foreign government to house illegals in our own country. This is nuts.

Musk also chimed in, calling it "Crazy."

Here's what X users had to say: 

What in the actual!

https://www.zerohedge.com/political/nuts-nyc-pays-pakistani-owned-roosevelt-hotel-220-million-house-illegal-aliens

Saturday, November 30, 2024

UK ultra-long mortgages push buyers past retirement

 More than a million mortgages have been issued in the past three years which home-buyers are set to still be repaying into pension age.

The latest data shows that two in five new mortgages have terms that see homeowners still making payments in retirement.

Ultra-long, or extended, mortgages have become more popular during a time of higher interest rates as people aim to spread the cost.

But this will ultimately make the loan more expensive, and experts say it raises serious questions over financial planning for retirement.

At the end of 2021, about three in 10 mortgages took repayments into pension age, according to Bank of England figures obtained by the pension consultancy LCP.

That proportion grew as interest rates rose. Despite interest rates having fallen from their peak, LCP said the trend appeared to have continued.

“There is increasing evidence that taking out a mortgage which runs past pension age is an entrenched feature of the mortgage market rather than a temporary blip," said Steve Webb, a former pensions minister who is now a partner at LCP.

"This has profound implications for retirement planning, as it is likely to mean that savers may end up using already inadequate pension pots to clear a mortgage balance."

The temptation for young homeowners is obvious. A longer mortgage term would reduce monthly repayments.

But with the average age of first-time buyers rising - it now stands at nearly 34 - the question of how people will be able to afford mortgage payments when they hope to retire becomes increasingly important.

UK Finance, the banking and lenders' trade body, said only 3% of mortgage-holders were currently paying off a mortgage after the age of 65.

While many young homeowners have chosen longer mortgage terms to make repayments more manageable, they may opt for shorter terms in the future if their salaries improve or they move house.

That is why UK Finance expects only a small fraction of the mortgages taken out now to ultimately go into borrowers' retirement years.

However, it does also raise the prospect of some people having to work longer until a mortgage is paid off, or they may choose to downsize.

Lenders set limits

Lenders are relatively flexible on allowing people to take out these longer-term mortgages, but there are constraints, according to David Hollingworth, from mortgage broker L&C.

"There will often still be maximum age limits at the end of the mortgage term and lenders will need to be sure that the borrowing will be affordable," he said.

"That will require borrowers to show that their post-retirement income is adequate."

Affordability checks became stricter after the financial crisis of nearly 20 years ago, with lenders needing proof that mortgage applicants could cope with rising interest rates.

The reality for many people is that getting any kind of mortgage remains unaffordable.

Data published earlier in the week shows the dynamics of renting and owning, and their effect on financial strains and life satisfaction.

"The proportion of people renting privately doubled during the 2000s, and while it has levelled off at around a fifth of households, or a third in London, we’re seeing people renting later in life," said Sarah Coles, from investment platform Hargreaves Lansdown.

"Even when people reach their late 50s and early 60s, 11% are still in private rentals."

https://www.bbc.com/news/articles/c704pv1jz5ro

Commercial Real Estate Bond Distress Reaches Record High

 Via SchiffGold.com,

From the national debt to negative jobs reports, data has been piling up that suggests America’s economic bubble is ready to burst. Now, with the Fed’s most recent round of rate cuts moving through the economy, fault lines are appearing in the commercial real estate sector.

The following article was originally published by the Mises Institute. The opinions expressed do not necessarily reflect those of Peter Schiff or SchiffGold.

Commercial real estate continues to suffer despite the Federal Reserve’s attempt at ameliorating the capital markets with a 50-basis point rate cut in September.

The pain is especially apparent in the so-called “CRE-CLO” bond market. CRE-CLO bonds are packaged commercial real estate mortgages comprising short-term floating rate loans. These bridge loans were recently, and most notably, used to facilitate the biggest apartment investment bubble in history, but were also used in financing other commercial real estate sectors including office, retail, hotel, industrial, and self-storage.

Most of the current batch of bridge loans originated in the 2020-2022 period—when benchmark rates were near zero and commercial real estate prices were peaking—and carried maturities of three to five years. Benchmark rates are now much higher, prices much lower, and property performance far worse than anticipated. Thus, a wall of maturities is staring borrowers, lenders, and bondholders in the face, all while underlying property performance disappoints.

Despite attempts by lenders to extend and pretend—kicking the can down the road in the short term to avoid defaults until the Federal Reserve lowers rates enough to bail them out—their delusions of reprieve may be fading fast.

Apartment Investors Play Checkers Instead of Chess

At the end of Q3, the distress rate for CRE-CLO loans across all commercial real estate sectors reached 13.1 percent, an all-time high. Distress in this instance is defined as any loan reported 30 days or more delinquent, past the maturity date, in special servicing (typically due to a drop in occupancy or a failure to meet certain performance criteria), or any combination thereof.

Figure 1

While roughly one in seven loans meets these criteria, the weakness is concentrated in two or three sectors.

Unsurprisingly, office properties have the highest rate of distress, with nearly one in five CRE-CLO office loans experiencing current distress. This is to be expected after the covid panic of 2020, subsequent to which various “work-from-home” directives essentially made the office market obsolete.

For similar reasons, distress is also high in the retail segment, as all but the most well-heeled retailers were forced under by the maniacal and criminal government edicts of the time.

However, the real story here is in the apartment, or multifamily, sector. Seen in Figure 1, the distress rate for apartments touched 16.4 percent in August. An astonishing number, indicating that one in six apartment bridge loans were distressed. The improvement to 13.7 percent shown for September is seasonal, as renters settle in at the start of the school year.

While this picture is bad enough, the reality under the surface is far worse. As reported by the Wall Street Journal, using Q2 data from MSCI, the batch of currently distressed apartment bridge loans comprise roughly $14 billion in total loans, but there exists an additional $81 billion in potentially distressed loans. MSCI categorizes loans as “potentially distressed” if they have seen delinquent payments, forbearance (when the lender lets interest payments accrue rather than taking a default action), or where key performance metrics like occupancy and net operating income are dangerously low.

Figure 2

The arithmetically-aware will note that if the $14 billion of currently distressed apartment bridge loans comprise a roughly 14 percent distress rate at the end of Q2 (as shown in Figure 1) and there are an additional $81 billion in potentially distressed loans not yet categorized as “currently distressed” (as shown in Figure 2), then MSCI data implies that 95 percent of all apartment bridge loans are either currently distressed or in imminent danger of distress.

While astounding, this level of distress will come as no surprise to veterans of the apartment market. In the 2020-22 period, bridge loans of this variety were ubiquitous above a certain minimum loan size. And, because of the extreme and reckless nature of money printing undertaken by the Federal Reserve during this time—when interest rates were effectively zero—lenders underwrote property acquisitions with a 1.0x debt service coverage ratio (“DSCR”), meaning the initial net operating income of the property was projected to just cover interest payments, with nothing left over.

Bridge loan interest rates floated at a spread (typically around 350 basis points, or 3.5 percent) to the Secured Overnight Financing Rate (“SOFR”), which was essentially 0 percent until mid-2022. Because of the 1.0x DSCR standard, a property acquired during this period that had net operating income of $1 million would have also had interest payments of $1 million at the then-prevailing interest rate of 3.5 percent.

SOFR is now 4.9 percent, indicating a total interest rate of 8.4 percent (SOFR + 3.5 percent spread). This same property now has interest payments of $2.4 million while net operating income is unlikely to have increased to any significant extent, if at all. Insurance and property tax increases in particular have damaged apartment profitability while rent increases have been difficult to execute in the face of stagnating real wages. By the same token, absurdly optimistic renovation plans have been impossible in the face of cash flows increasingly shunted towards paying interest.

The Amazing Disappearing Rate Cut

The high amount of potential distress in CRE-CLO bonds, and the loans that underlie them, indicate an expectation on the part of lenders that help is coming in the form of lower interest rates. After all, capital markets have become used to being bailed out by the Federal Reserve, all but demanding that the taxpayer—not they—be held responsible for their poor decisions. Nevertheless, the Fed’s recent rate cut is proving not to be the magic bullet on which lenders relied.

By August of this year, futures markets had fully priced in a 25-50 basis point Fed rate cut in September, and were expecting additional 25 basis point cuts in November and December. This expectation for the Fed Funds Rate carried over into Treasury yields, a key benchmark for the commercial real estate industry. Particularly important in the case of distressed bridge loans since any hopes of refinancing are placed not on more bridge loans—which are now much less pervasive—but on the fixed-rate agency market comprising Fannie- and Freddie-backed apartment loans, which prices loans off a spread to treasuries.

At the beginning of August, as markets priced in 75-100 bps of Fed rate cuts by year-end, 10-year Treasury yields reacted accordingly, dropping from 4.30 percent in late July (they had been 4.70 percent in April) to 3.65 percent in the middle of September. As of early November, most of that move had been erased—with yields back near 4.30 percent—roughly where they were prior to market pricing in this year’s Fed rate cuts.

Fear and Trembling

Undeniably, participants in the commercial real estate market—apartment bridge lenders in particular—are relying on loose monetary policy for their immediate salvation. They may get their wish. While Treasury rates have moved stubbornly higher, market forces only mean so much if the Fed decides to supplement rate cuts with purchases of treasuries, driving yields lower—another round of quantitative easing.

Nevertheless, to the extent they’re allowed to be heard, market signals are unmistakable. A regime that can’t stop spending and continues to appropriate the property of its citizens through inflation will provide upward pressure on Treasury yields, all else equal. In a free market context, the rent-seekers that comprise the commercial real estate market will have to work out their own salvation.

https://www.zerohedge.com/markets/commercial-real-estate-bond-distress-reaches-record-high

Tuesday, November 26, 2024

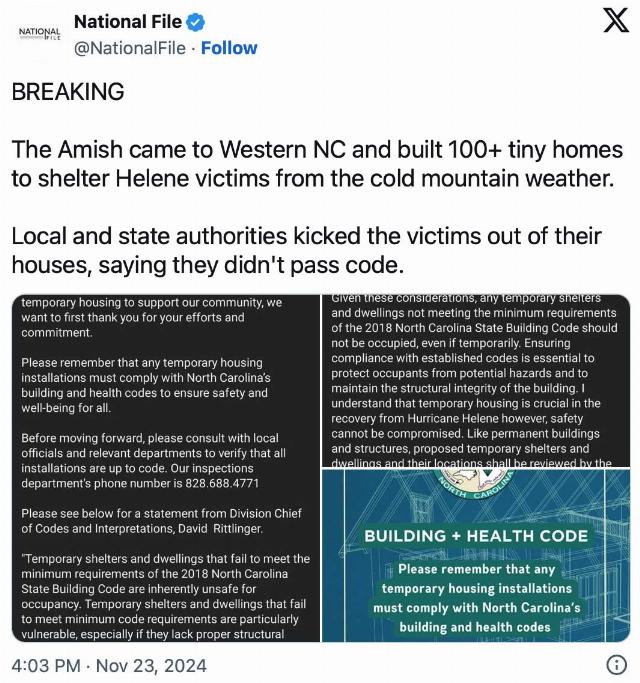
North Carolina dumps on hurricane survivors and the Amish

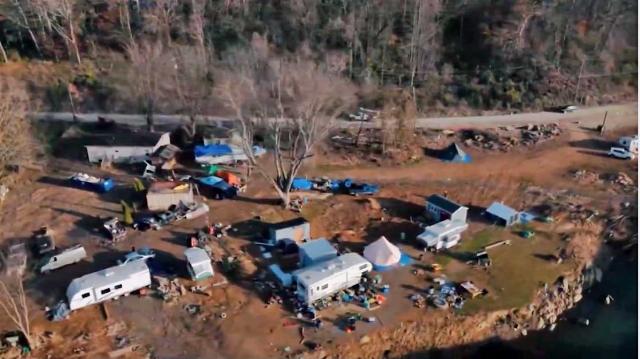
 After the horrific hurricane damage that destroyed or damaged as many as 100,000 homes in Western North Carolina, one would think FEMA and local officials would move heaven and earth to get those affected out of flimsy tents and trailers and into solid dwellings as winter inexorably descends. One would think wrongly:  

Graphic: Matt von Swol. Used with permission.

WNC resident (and X user) Margo reported last month that her area had "56 passenger bus load groups of skilled Amish carpenters coming down from Lancaster PA weekly to help build tiny homes for Cabins for Christ." Margo was doing her bit, looking for help finding room to lodge all of the volunteers. "We are bringing our own supplies and would be 100% self-sufficient," she posted, "Just need a place under [a] roof to sleep and house our volunteers from Monday night through Friday night every week."

That’s the kind of selflessness Americans have always revered. How many tiny homes have they built?

Teamed up with Cabins 4 Christ, the Amish volunteers have been working five-day shifts before swapping out for the next team of volunteers. Nobody seems to know how many tiny homes have been built. But I used my paid research assistant, ChatGPT, to do some investigating for me. For whatever it's worth, ChatGPT claims that "In disaster relief efforts, such as the recent North Carolina project, Amish carpenters often build small cabins in as little as 5 days."

If a small team can build a home each week, and there are hundreds of volunteers working for almost four weeks, they must have built more than a hundred quality cottages by now. All on their own dime. If you know anything about Amish carpentry, you might safely assume those little cottages are well-built.

So that sort of kindness, generocity and help must be welcomed, right? Right?

Of course not. There’s no indication the work of the Amish is dangerous, that it would in any way harm public health or safety. The Amish live simply, without all the gadgets and conveniences upon which most Americans rely, but they know how to build solid, warm shelter. After all, they live in Pennsylvania where they deal with cold every year. Shouldn’t local bureaucrats make whatever exceptions are necessary, even if only temporarily? FEMA is surely not taking up the slack, and though Donald Trump will likely turn his attention to that red taped agency, that’s going to take time, and winter is nearly upon us.

But the bureaucratic mindset, as explained by the invaluable Thomas Sowell, dominates even there, even now: 

“You will never understand bureaucracies until you understand that for bureaucrats procedure is everything and outcomes are nothing."

And so it goes as Joe Biden fades to transparency and his handlers howl in outrage and plot Trump’s, and America’s, destruction.

Mike McDaniel is a USAF veteran, classically trained musician, Japanese and European fencer, life-long athlete, firearm instructor, retired police officer and high school and college English teacher. He is a published author and blogger. His home blog is Stately McDaniel Manor. 

https://www.americanthinker.com/blog/2024/11/north_carolina_dumps_on_hurricane_survivors_and_the_amish.html

US New Home Sales Crashed In October

 After existing home sales unexpectedly ticked up in October, analysts expected new home sales to slow after their recent resurgence (-1.8% MoM). They were right... BUT... the magnitude is mind-boggling!

New Home Sales collapsed 17.3% MoM in October. That is the largest MoM drop since July 2013

Source: Bloomberg

That MoM plunge dragged sales down 9.4% YoY to 610k SAAR - the lowest since Nov 2022

Source: Bloomberg

Of course, all the revisions are lower...

Hurricanes Helene and Milton, which tore through parts of the Southeast, delayed sales in the nation’s biggest housing region and dragged down sales overall.

Sales in the South decreased 28% to 339,000, the slowest pace since April 2020. Sales also fell in the West, but rose in the Northeast and the Midwest.

Source: Bloomberg

Finally, we note that the median sale price of a new home increased to $437,300 in October, the highest in 14 months.

Does this mean November's data will see a massive surge in new home sales? ...even as rates have increased significantly?

https://www.zerohedge.com/personal-finance/us-new-home-sales-crashed-october

Monday, November 25, 2024

New York To Close 12 Migrant Shelters Ahead Of Trump Deportation Agenda

 New York is set to shutter 12 migrant shelters before the end of the year, marking a significant shift in its response to the city’s ongoing migrant crisis. The closures, announced just weeks before President-elect Donald Trump takes office for a second term, highlight the strain on resources and the political tensions surrounding immigration policies.

As Mike Shedlock of MishTalk.com noted in June, 20% of NYC hotels have become migrant shelters, driving up the cost of hotel rooms elsewhere for paying customers.

Two hotel-based shelters, the Hotel Merit in Manhattan and the Quality Inn JFK in Queens, have already been closed. An additional 10 facilities across the state - including in Albany, Dutchess, Erie, Orange, and Westchester counties - will cease operations by December 31, according to New York City Mayor Eric Adams’ office. The sprawling Randall’s Island shelter, which was designed to accommodate up to 3,000 migrants, is slated to close by February 2025, shortly after Trump’s inauguration.

A Crisis of Scale and Cost

Since the spring of 2022, more than 223,000 migrants and asylum seekers have arrived in New York City - roughly half the population of Albany. The city has struggled to house and support this influx, operating 210 city-run shelter sites across the five boroughs. Currently, 58,000 migrants remain in taxpayer-funded shelters, costing the city an estimated $352 per migrant per night. Only $130 of that amount goes directly to housing costs, with the rest allocated to social services, food, and cleaning.

Row NYC is a luxury hotel housing illegal migrants

The NYPD has spent $21 million on public safety and security related to the migrants.

The eye-popping figures, listed on the city’s online asylum-seeker funding tracker, shows the city overall spent $4.88 billion combined through fiscal years 2023 and ‘24. Based on the rate of spending, the city likely exceeded more than $112 million since the start of the new fiscal year beginning July 1, or will soon, cracking $5 billion.

Mayor Eric Adams’ administration has even projected the cost could double, hitting $10 billion over the three year period ending June 30, 2025. -NY Post

Without policy changes, the crisis is projected to cost New York taxpayers $12 billion over the next three fiscal years, according to city estimates. Mayor Adams praised efforts to consolidate shelter operations and reduce costs, noting a 19-week decline in the migrant census.

"Over the past two years, our teams have accomplished the Herculean task of providing compassionate care for a population twice the size of Albany and saving taxpayers billions of dollars," Adams said. "The new policies we’re implementing today will build on our successes, save taxpayers millions, and help even more migrants take their next steps towards fulfilling their American Dream."

Meanwhile, an audit released in August found that NYC overpaid upstate hotels by millions of dollars for sheltering illegal immigrants.

Of the questionable payments, $2.5 million were for unauthorized security, medical, and social services, $1.7 million for vacant rooms, and $230,000 for inflated food bills, according to the audit.

In another example, a Newburgh hotel billed a total of $57,000 for hundreds of unoccupied rooms in early May, for which DocGo got an additional $40,000 in commissions.

Tensions Over Shelter Evictions

Despite efforts to ease the burden on the system, the city’s shelter eviction policies have sparked controversy. Families issued a second 60-day eviction notice are now allowed to stay in their assigned shelters if they need more time, a move Adams touted as cost-saving and beneficial for children’s schooling continuity.

Hundreds of illegal immigrants or asylum seekers lined up outside of the Jacob K. Javits Federal Building in New York City on June 6, 2023. (David Dee Delgado/Getty Images)

However, adult migrants face stricter rules, with a policy permanently evicting them from city shelters after 30 days. The policy has drawn criticism from activist groups, including Jews For Racial & Economic Justice, which staged a protest at City Hall during a hearing on the issue.

"Immigrants are welcome here - Trumpian policy is not!" protesters chanted, accusing the city of violating its decades-old right-to-shelter rule, originally established to address homelessness. Activists called the eviction policy "cruel and destabilizing" before being removed from the chamber.

A Changing National Landscape

While the flow of migrants into New York has slowed, with fewer arrivals and a reported 101,790 encounters at the U.S.-Mexico border in September—the lowest since February 2021—concerns persist about potential surges before Trump’s border policies take effect. A caravan of 1,500 migrants in southern Mexico, near the Guatemala border, is reportedly attempting to cross before Trump’s inauguration.

Trump has pledged to implement strict immigration measures, including sealing the southern border, carrying out a large-scale deportation operation, and ending Biden administration parole programs and the CBP One app. South Dakota Governor Kristi Noem has been appointed as secretary of the Department of Homeland Security, with former ICE Director Tom Homan named "border czar."

As New York City consolidates its migrant operations, Adams has a tough road ahead. The closures signal a pivot in the city’s approach but also underscore the broader national debate on immigration policy.

https://www.zerohedge.com/political/new-york-close-12-migrant-shelters-ahead-trump-deportation-agenda