Search This Blog

Wednesday, October 14, 2026

More Adult Kids Going ‘No Contact’ With Parents. How Will It Affect Generational Wealth?

 Family dynamics and expectations change with every generation. And a perceived rise in estrangements between adult children and their parents is the latest shift that could have an impact on the housing market and intergenerational wealth transfer. 

According to some reporting and anecdotes from experts, more adult children are estranged from or going “no contact” with their parents.

Estrangement is difficult and complicated for many reasons, but one major downstream effect is what happens to assets such as real estate and proceeds from home sales when a family’s bonds are broken.

As the Great Wealth Transfer sends trillions of dollars from older generations to younger folks, disinheritance means substantial sums of money may go in different directions than expected, if the parents decide to redirect it.

What estrangement means for any one family depends on its circumstances. 

Why estrangement may be on the rise

It’s difficult to pin down exactly how prevalent a trend like estrangement among family is. One YouGov poll from 2025 says that 16% of American adults are estranged from their parents and that the children are twice as likely to cut off contact from their parents than vice versa. 

“I’ve certainly noticed an uptick in parent-children estrangement and disinheritance,” says Evan Farr, a certified elder law attorney and retirement planner in Virginia, Maryland, and Washington, DC. “But it's still quite rare. However, it shows up in client meetings and consultations far more frequently than it did 10 or 15 years ago.”

The YouGov poll cites abuse, manipulative behavior, and lies or betrayal as the most common reasons for estrangement of children from their parents. The Wall Street Journal argues that the rise is partly due to the increased use of words like “toxic” and “abusive” to describe familial relationships.

For his part, Farr notes that several factors may be at play, including cultural changes. However, the most common scenario he sees is parents disinheriting children over their choice of partner. 

“The parents then believe that their child is either being taken advantage of or controlled by a ‘bad’ son-in-law or daughter-in-law and ultimately decide to disinherit their child,” he says. 

How estrangement affects inheritance

Because estrangement has no legal status, it doesn’t change who inherits, the way a deliberate estate plan does.

“An estranged child typically has the exact same rights of inheritance as every other child, regardless of if the estranged child hasn't spoken to their parents in 20 years,” says Farr. 

If one or both sides of the relationship truly wish to sever ties, it’s best not to leave any ambiguity.

“If a parent intentionally wants to disinherit a child, it needs to be done carefully and clearly under their state’s law,” says Pamela Garrett, an attorney and the owner of Law Mother Asset Protection & Estate Planning. “Simply leaving the child’s name out of a will can create questions about whether they were forgotten or intentionally excluded.”

On the flip side, estranged children may still need to take steps to wash their hands of their parents’ estate. 

“Estrangement may end a relationship, but it doesn’t necessarily end the legal connection,” says Garrett. “Without an estate plan, the law may still give that child inheritance rights, even if the family hasn’t known where they are for years. If an heir truly doesn’t want the property, they may be able to disclaim the inheritance, depending on the circumstances and state law.”

Disclaiming an inheritance is complex, and the laws around it vary depending on where you live. Farr notes that in Virginia, if an estate plan doesn’t provide what happens next, “a disclaimed interest shall pass as though the disclaiming beneficiary had died ... which could result in the inheritance passing down to the beneficiaries’ own children, thus creating unforeseen and often undesired results.”

The big picture of homeownership

What and how much is at stake if older people won’t have their children as obvious heirs to their major assets, including their homes? 

“More estrangement will mean more parents possibly redirecting their estates away from their children and toward grandchildren, other relatives, charities, or even friends who have played important roles in their lives,” says Farr. “It may also lead to more inheritance litigation—especially where one child is left substantially less than siblings or nothing at all.”

Many homeowners hold on to a house until death, and typically this can benefit their heirs. A “stepped-up basis” resets the home’s value for tax purposes to what it’s worth on the date of the owner’s death, so decades of appreciation can pass to the heirs free of capital gains tax. A home gifted during the owner’s life gets no such reset. An owner who sells while alive can exclude up to $250,000 of gain on a primary residence ($500,000 for married couples filing jointly), but anything above that is taxable.

Because the step-up goes to any heir, estrangement from a child doesn’t remove the incentive to hold. It weakens when the owner plans to give the home’s value away or spend it down.

“Some parents who become estranged from their children decide to spend more of their wealth during their lifetimes rather than preserving it for an inheritance,” says Farr. 

For some owners, spending down could include selling the home, which would add to housing supply. Realtor.com® estimates that 13.9 million homes currently owned by baby boomers and the Silent Generation are expected to be released back into the market in the next 10 years, and even a small uptick could make a difference in inventory-strained markets on the coasts.

Making a clean break from a parent is complicated when big financial questions are still open. For adult children who wish to remain estranged, know that there still may be major legal and logistical questions to address at some point—not to mention the financial and emotional questions that arise when the family home needs to be sold or otherwise addressed after the parents die. 

The parents, meanwhile, should make plans and not leave things open-ended. Even if reconciliation is possible and those plans may change again down the road, there are ways to get out ahead of additional tension and heartache. 

“Sometimes,” says Garrett, “the better estate plan is to create a clear path for the property to be sold and the proceeds distributed rather than leaving your family to figure it out after you’re gone.”

https://www.realtor.com/news/trends/adult-kids-no-contact-wealth-transfer/

Sunday, October 4, 2026

Mamdani’s deadly double standard for NYC apartment rehabs

 Why do progressives refuse to see how they’re killing the city’s housing market?

Consider Mayor Zohran Mamdani’s proud notice that Brooklyn’s Nostrand Houses complex is getting over $600 million in pubic support to rehab almost 1,200 NYCHA apartments, which works out to over $500,000 a unit — even as the state and city deny private landlords’ needs to spend anything like that to get their vacant apartments up to code.

NYCHA is falling apart, with a capital-needs shortfall approaching $100 billion; that’s how badly public ownership of residential apartments has failed the city.

Yet private owners of rental apartments are blocked by law from raising the rent to cover the cost of rehabbing their units — so tens of thousands of rent-regulated apartments sit empty, off the market needlessly.

State progressives’ 2019 law pretends to protect low-income tenants with this mandate, when in fact poor and non-poor suffer from a shrinking housing supply.

NYCHA will never get all the cash it needs to stop many complexes from falling apart completely, while private landlords only want a chance to improve their buildings without having the government’s heavy hand artificially depressing prices.

When running for mayor, Mamdani claimed, “For those landlords who need a little extra help, there’s a city fund they can apply to.”

Huh? When pressed for details on this city fund, the mayor’s office stonewalls.

Because no such fund will give landlords money to repair their buildings; at most, the city offers financing, but only if you enter covenants that impose even higher costs.

Nowhere else does the city forbid price increases: People need underwear and shoes, but nobody expects the government to force stores to sell them below cost.

It doesn’t work for housing, either — but the “social justice” crew doesn’t care.

If they have their way long enough, the entire city housing market will be a disaster as bad as NYCHA.

https://nypost.com/2026/10/04/opinion/mamdanis-deadly-double-standard-for-nyc-apartment-rehabs/

Thursday, October 1, 2026

Mamdani’s $607M NYCHA makeover costs taxpayers a staggering $528K per apartment

 Mayor Zohran Mamdani just inked a public housing rehab so pricey it works out to more than half a million dollars for every single apartment — on city taxpayers’ dime.

The city closed financing Tuesday on a $607 million overhaul of Nostrand Houses, the aging NYCHA complex in Sheepshead Bay, Brooklyn. 

Spread across the development’s 1,148 units, the math lands at roughly $528,700 per apartment. That’s nearly $38 million for each of the campus’s 16 buildings and north of $300,000 for every one of its roughly 2,000 tenants.

Mayor Zohran Mamdani’s administration closed financing on a $607 million overhaul of Brooklyn’s Nostrand Houses, a price that works out to roughly $528,700 for each of the complex’s 1,148 apartments and sparked immediate backlash online over the cost.Paul Martinka for NY Post

Jay Martin, head of the landlord group Community Housing Improvement Program, didn’t mince words either.

“My criticism is not about NYCHA getting needed repairs,” Martin wrote on X. “It’s not that those repairs cost $522,000 per unit. It’s not even that the average NYCHA unit costs 80% more per month to operate than a pre-1974 rent-stabilized unit. 

“It’s the inability to acknowledge that hundreds of thousands of private rent-stabilized units have rents that don’t cover operating costs.”

The money pays for gutted and rebuilt kitchens and bathrooms, new elevators and heating systems, lead and mold cleanup, accessibility upgrades and beefed-up security for about 2,000 residents. Pictured is a rendering of a living space of what a unit will look like following renovations.Paul Martinka for NY Post

Those units get a rent freeze and show trials. Public housing gets billions of dollars. City Hall, meanwhile, was popping champagne.

“This $607 million investment means new kitchens, safer and healthier apartments, modern building systems and the dignity of a home that works the way it should,” Mamdani said in a statement.

So what exactly does half a million bucks buy in Sheepshead Bay?

It is the first deal completed under the Public Housing Preservation Trust, which keeps the development public while roughly doubling its federal subsidy, and it is backed by a mix of city, federal and private financing. A second rendering is shown.Paul Martinka for NY Post

Kitchens and bathrooms will be gutted down to the studs and rebuilt with quartz countertops, new appliances, fresh plumbing and scratch-resistant floors. Every apartment gets double-pane windows, new intercoms, laundry hookups and window heat pumps that let tenants control their own heat and AC. Crews will also scrub out lead and mold hazards.

Building-wide, the money covers new elevators, boilers and hot water systems, rewired electrical, expanded security cameras and an on-site guard. Officials said 81 units will be retrofitted for residents with mobility needs and another 48 for those with vision or hearing loss. A new management office will house more than 40 staffers.

The project is the first to cross the finish line under the Public Housing Preservation Trust, a state-created entity that lets NYCHA developments swap traditional federal funding for the more generous Section 8 pipeline while staying in public hands. 

Nostrand residents voted to join back in December 2023. City officials said the switch roughly doubles the federal operating subsidy the complex collects.

“This $607 million investment gives us the resources to deliver the modernization residents have been waiting for while keeping Nostrand fully public and preserving resident rights and affordability,” Trust President Vlada Kenniff said.

The deal pulls in money from the Office of Management and Budget and the Housing Development Corporation (HUD), Merchants Capital and the AFL-CIO Housing Investment Trust, with the city’s building trades unions signed on as labor partner.

The administration has not released a line-by-line breakdown showing how much of the $607 million goes to actual construction versus financing, reserves and other soft costs.

Construction is slated to start this fall.

“Residents have helped shape these plans from the beginning, and now we are one step closer to seeing the improvements we’ve been waiting for become a reality,” said Miriam Rodriguez, a Nostrand tenant who sits on the Trust’s board.

The timing is raising eyebrows in the private market.

The bill lands just as Mamdani’s hand-picked Rent Guidelines Board slaps a two-year freeze on roughly 1 million rent-stabilized apartments, taking effect on leases starting Thursday. Owners of those buildings, many of them pre-war walk-ups, say they’re being squeezed between flat rents and soaring bills for insurance, fuel and upkeep.

“Older rent-stabilized buildings are already struggling under rising operating costs, yet the Board chose to disregard those realities,” Real Estate Board of New York President James Whelan said after the June vote.

Mamdani has made NYCHA the centerpiece of his housing agenda, pouring $5.6 billion in capital funds into public housing in his first budget. Three more developments, Bronx River Addition, Unity Towers and Hylan Houses, have already voted to follow Nostrand into the Trust.

https://nypost.com/2026/10/01/real-estate/mamdanis-reveals-607m-public-nycha-makeover/

Sunday, September 27, 2026

'Bed Bath & Beyond Inc. changes corporate name again, relocates headquarters'


  • Bed Bath & Beyond Inc. is changing its corporate name to Neighborhood Intelligence and will begin trading on the Nasdaq under the ticker symbol NXH, effective Aug. 17. As a result, the company’s last day trading on the New York Stock Exchange will be Aug. 14.
  • The company is also relocating its headquarters from Murray, Utah, to Nashville, Tennessee, according to a Tuesday announcement.
  • The changes underscore the company’s three-pillared turnaround strategy, focused on omnichannel retail and commerce; digital, financial, insurance and blockchain services; and beyond home, which includes an AI-powered home operating system.

The corporate name change and headquarters relocation mark the latest moves from the company to establish the next era of Bed Bath & Beyond.

CEO Marcus Lemonis reiterated the company’s ambitions to move beyond being a retailer, hoping to be a part of customers’ lives in every aspect of their home — from flooring to insurance.

“Retail can only introduce us to the customer. Home services allow us to deepen that trust. Quite frankly, it’s where the real margin exists,” Lemonis said on a call with analysts Tuesday. “When a customer invites us across the threshold, they’re trusting us with an expansive and disruptive project inside of their home where their families live.” 

Lemonis called out recent acquisitions — like Closet Works and Lumber Liquidators, as well as real estate brokerage firm Fathom — as helping it to build out the service component for customers.

The company’s plan to expand beyond retail has “some merit,” according to GlobalData Managing Director Neil Saunders. “We are concerned that the vision is too lofty in aspiration and too lacking in detail and precision. And ultimately, that might prove its undoing – especially in terms of how it’s presented to the customer,” he said.

Bed Bath & Beyond on Tuesday also reported second quarter earnings results. Revenue in the period increased 28% year over year to $361 million, which the company said marks its second consecutive quarter of year-over-year revenue growth after 19 quarters of declines.

“While two quarters are not a victory, and the work is far from finished, what matters is that the operating model is now producing measurable evidence that it is working — revenue growth, order growth, margin expansion and early integration results from the businesses we’ve acquired,” Lemonis said.

Though much of that growth is thanks to the acquisitions Bed Bath & Beyond made, particularly the deal to acquire The Brand House Collective (formerly Kirkland’s Home), which closed in the second quarter.

Last year, when The Brand House Collective was a stand-alone business, the company reported Q2 2025 net sales of $75.8 million. “If that’s factored in, growth for the two combined businesses comes in at a much less impressive 0.9% on a simple pro forma basis,” Saunders said in emailed comments. “The periods are not perfectly aligned, but the calculation provides a much better indication of the underlying performance which, honestly, isn’t all that impressive given it comes in below overall market growth.”

The recent acquisitions also increased the company’s active customer base to 6.4 million, up 47% year over year, and orders delivered to 2.8 million. But Bed Bath & Beyond’s net loss expanded in the quarter, reaching $39 million from $19 million a year ago.

“The proof point in whether this vision can successfully come to life will ultimately come from being able to generate sustained top line growth with some good profitability – which will also rely on finding high synergistic cost savings,” Saunders said.

Looking ahead, the company expects Q3 revenue to be between $505 million and $525 million, with margins expected to be around 30%.

https://www.retaildive.com/news/bed-bath-beyond-corporate-name-neighborhood-intelligence-headquarters-second-quarter-earnings/827083/

Saturday, September 26, 2026

The Commercial Real Estate Crash Is Moving From Paper Losses To Realized Losses

 The great commercial real estate waiting game may finally be running out of time, according to Bloomberg.

For years after Covid fundamentally changed how Americans use office space, lenders and property owners managed to postpone much of the financial damage. Loans were modified, maturities were pushed out and buildings were given more time to recover. The basic assumption was that eventually interest rates would come down, employees would spend more time downtown and refinancing markets would reopen.

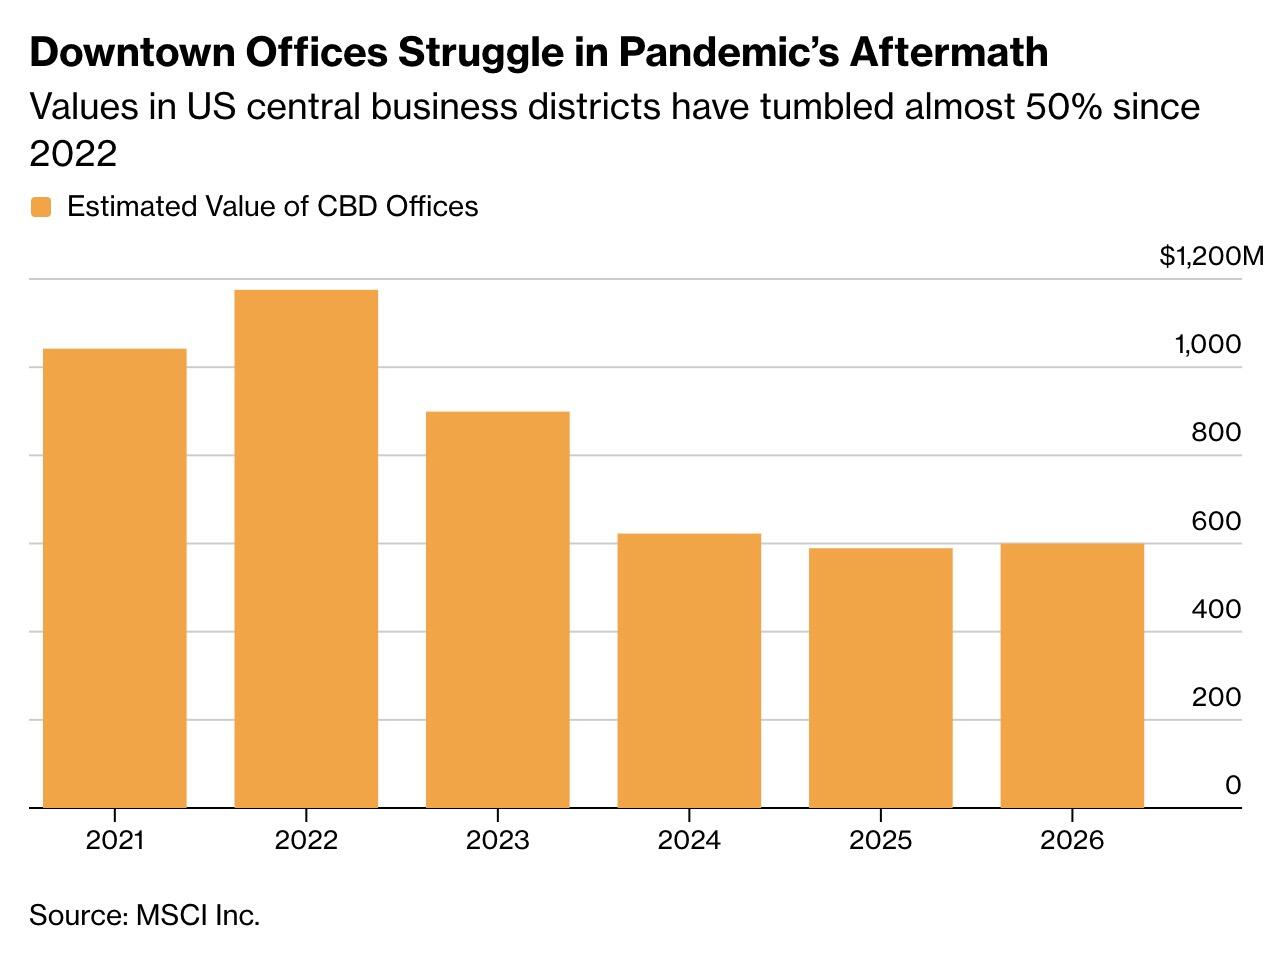
Instead, many owners are reaching the end of the runway with rates still elevated and buildings worth dramatically less than the debt sitting against them.

Chicago’s Aon Center offers an almost absurd illustration. The 83-story skyscraper changed hands for $712 million in 2015 and was subsequently refinanced, with $536 million of debt eventually packaged into commercial mortgage-backed securities. Today, after losing important tenants, the building is worth nowhere near that amount. Its latest appraisal came in at just $195 million — a decline of roughly 73% from its 2015 purchase price.

Bloomberg writes that when the debt matured in July, the owner couldn’t repay it and sought another three years to sort things out. This time the lender wasn’t interested. The request was “unequivocally denied.”

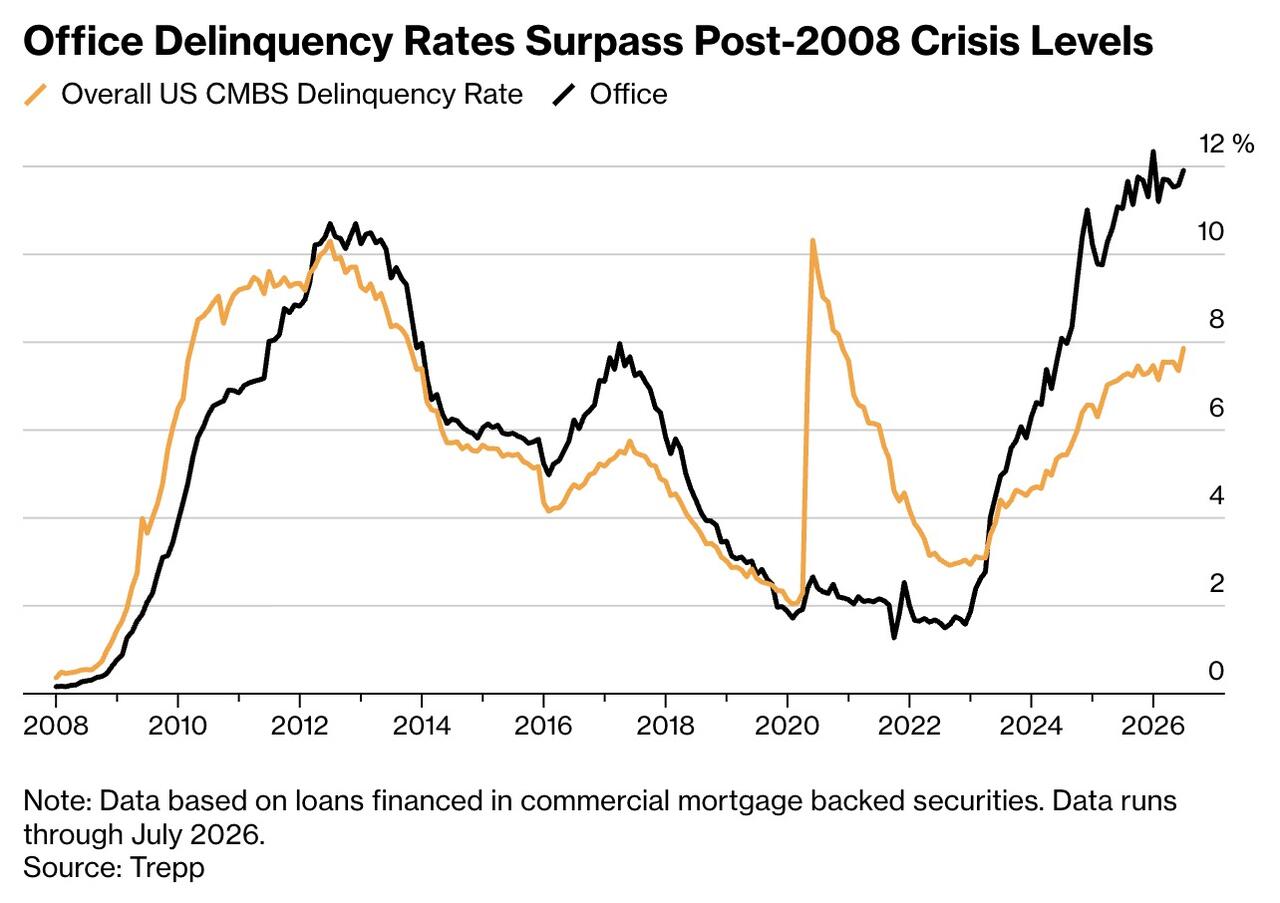
Situations like this are beginning to pile up across the country. Office loans packaged into CMBS are now delinquent at a 12% rate, according to Trepp. That puts distress near an all-time high and, remarkably, beyond the levels seen in the aftermath of the 2008 financial crisis. Meanwhile, approximately $64 billion of office CMBS loans come due this year and next. Nearly $40 billion of that pile is already delinquent, in default or flagged as potentially troubled.

But this isn’t one uniform nationwide office collapse.

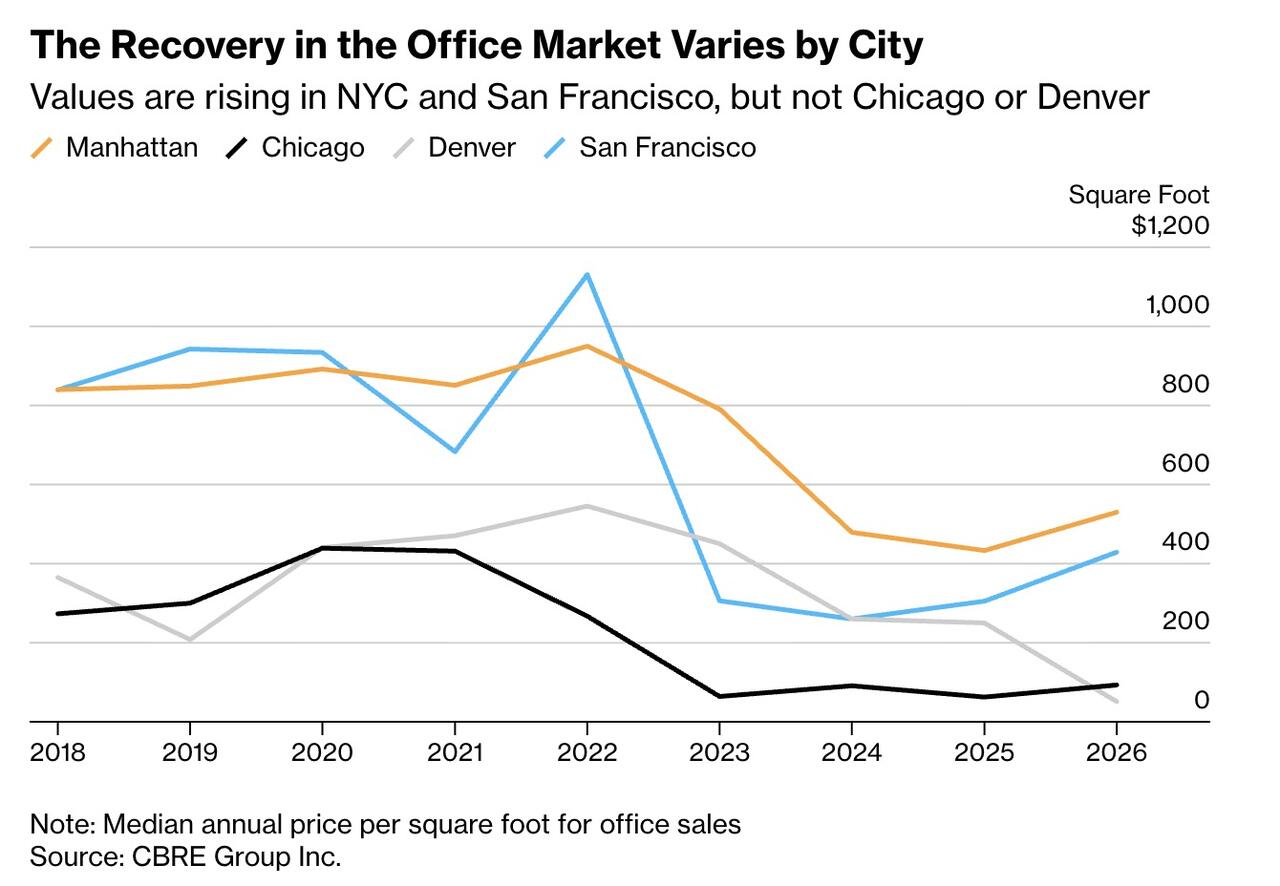
New York has been surprisingly resilient, with finance, law and technology companies still competing for desirable space. San Francisco, despite enormous problems left over from the pandemic, has received a new source of demand from the AI boom.

Other cities have considerably less working in their favor. Chicago’s downtown office vacancy rate is roughly 27%. Denver’s has reached an astonishing 39%. Los Angeles and several other downtown markets are also struggling, especially in areas dominated by older office stock.

There’s also increasingly a tale of two office markets within individual cities. Companies willing to spend money on office space generally want newer buildings, good locations and modern amenities. That leaves yesterday’s Class B towers fighting over a shrinking pool of tenants while their economics deteriorate.

And some of the repricing has been brutal.

Denver’s Republic Plaza has lost roughly 80% of its value compared with when Brookfield financed the property in 2012. Chicago’s Citadel Center recently changed hands for $137 million, approximately 76% below what the building sold for in 2006. The situation is bad enough that CoStar expects roughly 11.5 million square feet of Chicago-area office space to simply disappear through demolition by 2031.

Even those enormous valuation declines may understate what lenders ultimately recover.

Distressed office properties sold this year have fetched prices roughly 20% below their latest appraisals, according to Deutsche Bank research cited in the report. In other words, marking a building down dramatically on paper doesn’t necessarily mean you’ve marked it down enough.

There is, however, another side to the collapse. Once prices fall far enough, someone eventually decides the risk is worth taking. That process is now beginning. Investors are stepping into buildings at fractions of their former valuations, effectively resetting the cost basis of properties that made little economic sense at yesterday’s prices.

The same 601W connected to the troubled Aon Center recently bought Chicago’s 175 West Jackson Boulevard for only $41 million, nearly 90% below its pre-Covid sale price. Elsewhere in Chicago, investors acquired the debt behind another major tower for around $100 million, roughly 76% below the building’s previous purchase price.

That’s probably the most important part of what is happening now. An office recovery doesn’t necessarily require these buildings to regain anything close to their old valuations. It requires the old valuations to finally die.

For years, the industry could avoid discovering what many of these buildings were actually worth because lenders kept extending loans and owners kept waiting. As maturities arrive and extensions become harder to obtain, those theoretical losses increasingly have to become actual ones.

And only after that happens can buildings move into new hands at prices that make sense in the post-Covid world. As Polpo Capital’s Dan McNamara put it: “One of the scariest headlines is that office CMBS delinquencies are higher than after 2008.”

“And it’s going to go higher as we face more maturities.”

https://www.zerohedge.com/markets/commercial-real-estate-crash-moving-paper-losses-realized-losses

Wednesday, September 23, 2026

More US Homebuyers Apply For Riskier Mortgages As Interest Rates Top 7%

 by Andrew Moran via The Epoch Times,

Higher interest rates pushed prospective homebuyers toward riskier mortgages last week, new industry data show.

The total volume of mortgage applications declined almost 2 percent for the week ending Sept. 18, according to a report released by the Mortgage Bankers Association on Sept. 23. This represented the third consecutive weekly drop.

Applications for a mortgage to purchase a home fell 1 percent and were down 11 percent from the same time a year ago. Refinancing applications also fell to their lowest levels since February 2025, down 3 percent monthly, and were 62 percent lower year over year.

"Applications for both refinance and purchase loans declined further last week, noting that the comparison is to the week that included the Labor Day holiday," Mike Fratantoni, the group's senior vice president and chief economist, said in a news release.

Last week's decline aligned with the sharp increase in interest rates.

Because fixed-rate mortgage costs have accelerated in recent weeks, borrowers sought riskier adjustable-rate mortgages - also known as ARMs - Fratantoni added.

"With fixed rates much higher, more borrowers opted for ARMs, with the ARM share reaching 9.8%, as rates for 5/1 ARMs were more than a percentage point lower than those for fixed rate loans," he said in a statement.

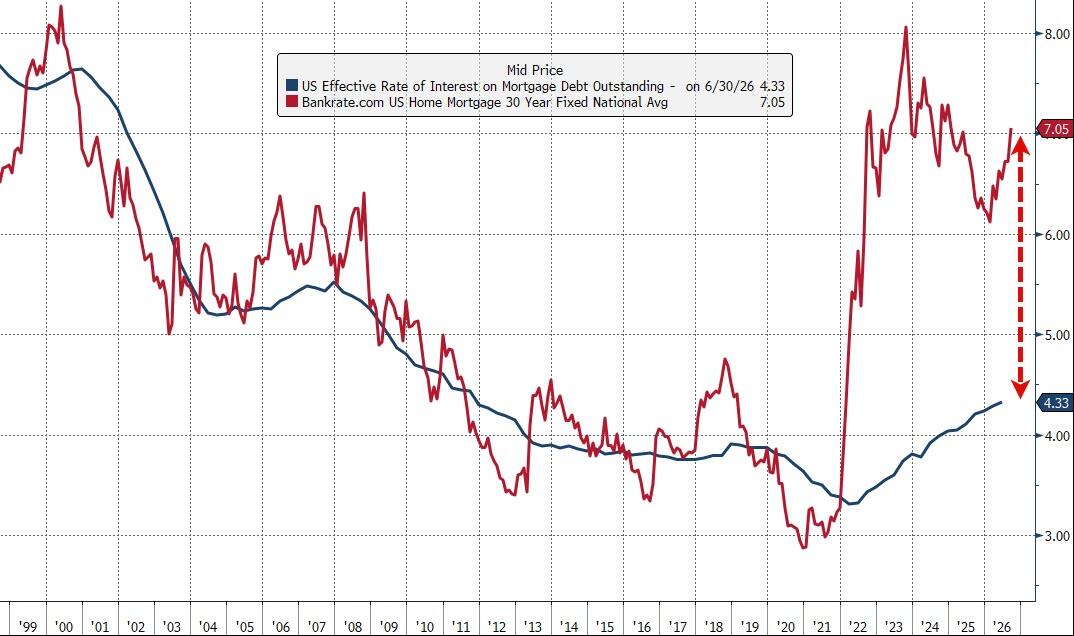
The average contract interest rate for 30-year fixed-rate mortgages rose to 7.12 percent, from 6.97 percent - the highest since May 2024.

Mortgage rates have increased by more than 100 basis points since the United States and Israel launched a joint military operation against Iran in late February. The conflict, approaching the seven-month mark, has sent Treasury bond yields surging.

The benchmark 10-year Treasury yield reached 5 percent again midweek, up from 3.96 percent before the war in Iran began. The mortgage market generally tracks government bond yields, resulting in higher borrowing costs for prospective buyers.

ARMs start with a lower fixed rate for three to ten years, then change every six months or annually based on market conditions. This product saves borrowers money upfront but can swing higher or lower based on benchmark rates.

Mortgage rates have ticked up slightly so far this week.

As of Sept. 22, the average 30-year fixed rate was 7.17 percent, according to Mortgage News Daily.

Fueling Interest Rates

Global energy markets and inflation data have been the driving forces behind interest rates and will determine the Federal Reserve's next policy decision, says Jeff DerGurahian, head economist at loanDepot.

"For now, rates appear to be standing at a fork in the road. Softer inflation and lower oil prices could provide relief, while continued energy pressure could keep mortgage rates near or above 7%," DerGurahian said in a note emailed to The Epoch Times.

Crude prices have fallen sharply this week, with U.S. oil down about 10 percent to around $91 per barrel. Brent, the international benchmark, returned above $100 midweek.

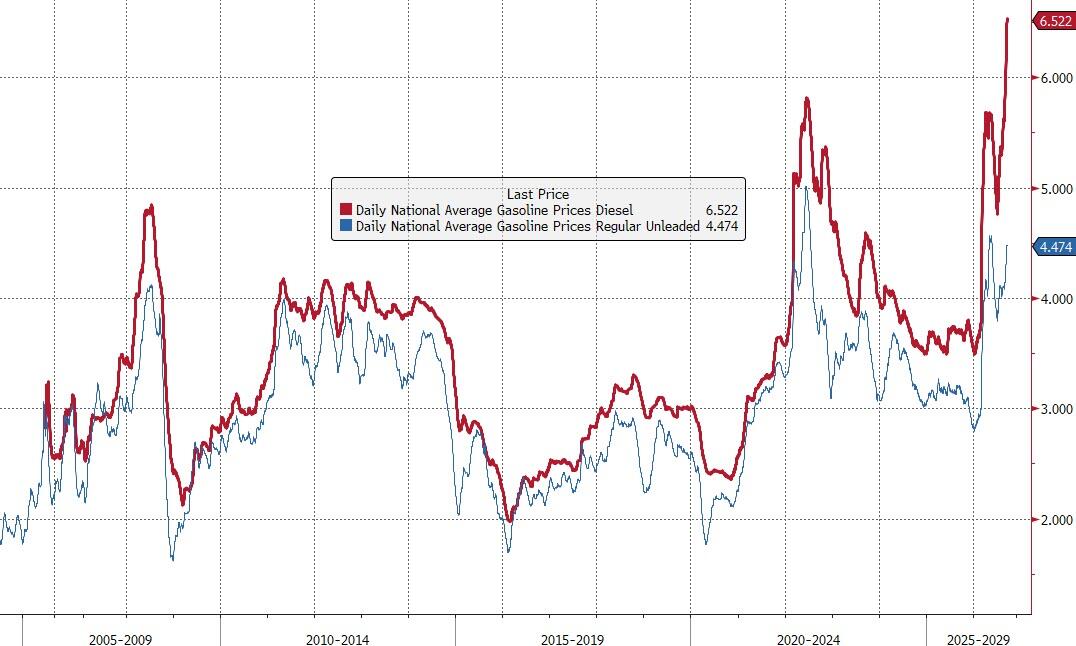
As of Sept. 22, the national average for a gallon of diesel has risen to $6.52, according to the American Automobile Association.

Meanwhile, the next major inflation report will be August's personal consumption expenditures (PCE) price index, the Fed's go-to inflation measure.

After that, the September consumer price index report will be released in mid-October.

The Cleveland Fed projects annual headline consumer inflation will jump to 3.5 percent, but core inflation, which strips out volatile energy and food prices, will hold steady at 2.4 percent.

Until then, investors are leaning toward another quarter-point rate hike at the October Federal Open Market Committee policy meeting after the Fed followed through last week on the first increase to the benchmark federal funds rate since July 2023.

"Those expectations are not set in stone though," DerGurahian said.

"If oil prices move lower or the September core inflation reading comes in softer than expected, the October hike could be pushed further out. Continued improvement could even cause markets to remove one of the three future hikes currently priced in."

Fed Chairman Kevin Warsh will hold the next two-day meeting on Oct. 27 and 28.

https://www.zerohedge.com/personal-finance/more-us-homebuyers-apply-riskier-mortgages-interest-rates-top-7